

The art world has never had more information and never been harder to read. Every week produces another fair report, auction result, gallery announcement, museum opening, brand activation, biennial list, studio visit, collector dinner, and market rumour. None of it is scarce. What is scarce is interpretation.
For most of the last two decades, the market ran on a stable hierarchy of signals. Gallery representation. Institutional validation. Auction performance. Collector interest. Critical writing. Fair visibility. Proximity to the right people. Those signals still matter. They have just stopped meaning one thing each.
A gallery show now signals conviction or inventory pressure. An auction record signals demand or financial engineering. A luxury collaboration signals cultural credibility or borrowed aesthetics. An artist who is everywhere signals momentum or exhaustion. A collector who goes quiet signals absence or acquisition.
Watch how this plays out right now, in real time. This May, the New York marquee sales pulled in around $2.5 billion, almost double the previous spring, the best collective result in three years. Read the headline and the market is roaring back. Read the structure and a record 79% of evening-sale turnover was covered by guarantees, the totals still trailed 2014, 2015, and 2019, and most of the fireworks came from a single estate, the S.I. Newhouse collection at Christie’s, which alone made $631 million. The market is not roaring. A handful of guaranteed trophies are roaring, and the room is doing the maths quietly.
That gap, between the headline and the structure underneath it, is the whole reason signals matter.
A signal is not a prediction. It is a clue. One signal in isolation will mislead you. Several signals moving in the same direction will show you a shift before it becomes consensus and before the price reflects it.
This is the Signal Map: twenty signals to read across artists, galleries, collectors, institutions, luxury, visibility, and market behaviour, built on data from Art Basel and UBS, Artnet, Deloitte and ArtTactic, Bank of America, Bernstein, and HSBC, and tested against the spring 2026 season as it happens. The first eight are below. The remaining twelve, the ones that move money and reputation quietly, are for the TAB Intelligence Desk members.
1. Recovery is not the same as confidence
A market can recover in value long before it recovers in nerve.
The split runs straight through the current numbers. Across 2025 the market grew 4% to $59.6 billion, the first growth after two years of decline, but the gains concentrate almost entirely at the top. Work priced above $1 million accounts for less than 1% of auction lots and 54% of total value. Sales above $10 million grew 30% in a year. Work under $50,000, which is 95% of all auction transactions, fell 2%. The spring 2026 sales repeated the pattern in miniature: liquidity at the very top, hesitation everywhere beneath it. So the market is growing. Most of the market is not feeling it.
When strength gathers this tightly around the safest names, the question is never whether things are selling. It is where confidence is concentrating, and whether anyone outside the trophy tier can feel it.
Watch for: which price bands are actually moving, which artists are being protected by their galleries, and whether buyers are acting across the board or only around a dozen blue-chip names.
2. The headline number is the least useful number
A big top-line figure does one job well. It reassures people who need reassuring.
But aggregates aggregate. They average. They smooth. And in a market this unequal, smoothing is a form of hiding. The honest reading of the recovery is not “the market grew.” It is “a few estates did a disproportionate share of the lifting.” Across the big three houses, single-owner sales jumped to 38% of New York auction value, against a 7% average in the second half of the last decade. The Leonard A. Lauder collection moved $531.3 million in a single autumn. This spring, Newhouse moved $631 million in a single night. Pull the estates out and the picture flattens from recovery to stabilisation.
You can see it in the softer counts too. The US market opened 2025 down 5.6% in the first half, its third consecutive first-half contraction, before the autumn estates rescued the annual figure. The headline turns positive when great collections come to market, not when demand broadens.
Watch for: what is carrying a result. A market lifted by three estates and a wealth-transfer moment is not the same market as one lifted by broad demand, even when the top-line number is identical.
3. The middle market is hollowing out, not cooling
This is the signal almost no one is pricing correctly.
Sales of work priced between $50,000 and $250,000 are down 29% since 2010. That is not a soft patch. It is a structural hollowing that has run for fifteen years under cover of strong top-end and strong bottom-end numbers. It is sharpening at the business level now: among dealers turning over $250,000 to $500,000, 45% report falling margins, the worst reading of any segment, and many report it while still growing sales. Selling more and earning less is the defining condition of the middle.
The top is insulated by scarcity and trophy logic. The bottom stays liquid because entry is cheap. The middle carries the overhead, the staff, the fair costs, and the artists who need sustained support rather than a single hot moment. The gallery closures clustering around emerging and mid-tier programmes are not bad luck. They are the middle giving way. Hold one caveat: Deloitte and ArtTactic still flag the wider $50,000 to $1 million band, worth roughly $8 billion, as a relative bright spot and an entry point for new buyers. The squeeze is real and the opening is real, which is exactly why the price point you watch matters.
Watch for: galleries cutting fair participation, artists changing representation, collectors negotiating harder, and the exact price point where enthusiasm turns into hesitation. That point is your stress gauge.
4. Visibility has become expensive and unreliable
The art world confused visibility with value for a decade, and the bill is arriving.
Online sales have fallen to $9.2 billion, the lowest since 2019, as serious money moves back into rooms and relationships. More than half the value of offline auctions comes from work above $1 million, and those works are roughly 2% of online-only value. The internet never moved the top of the market online. It expanded the bottom, where new buyers experiment and exit.
The sharpest evidence sits in ultra-contemporary, the artists born after 1974 who carried the hype cycle. The segment has cooled for four straight years, and the average price for an ultra-contemporary work at auction has fallen to $15,629, a decade low, down 72.4% from its 2021 peak. The artists who became visible fastest are the ones whose prices fell furthest. Even the spring 2026 rebound was selective about this: Anna Weyant, long cited as emblematic of the Covid-era boom and its excess, posted her strongest result since 2022, but the recovery reached named survivors, not the category.
Visibility builds recognition. It does not build a career, and past a certain velocity it eats the work before the work can deepen.
Watch for: whether an artist’s visibility comes with discipline. Selective shows. Consistent development. Careful pricing. Real writing. Curatorial context. Visibility without those is a countdown.
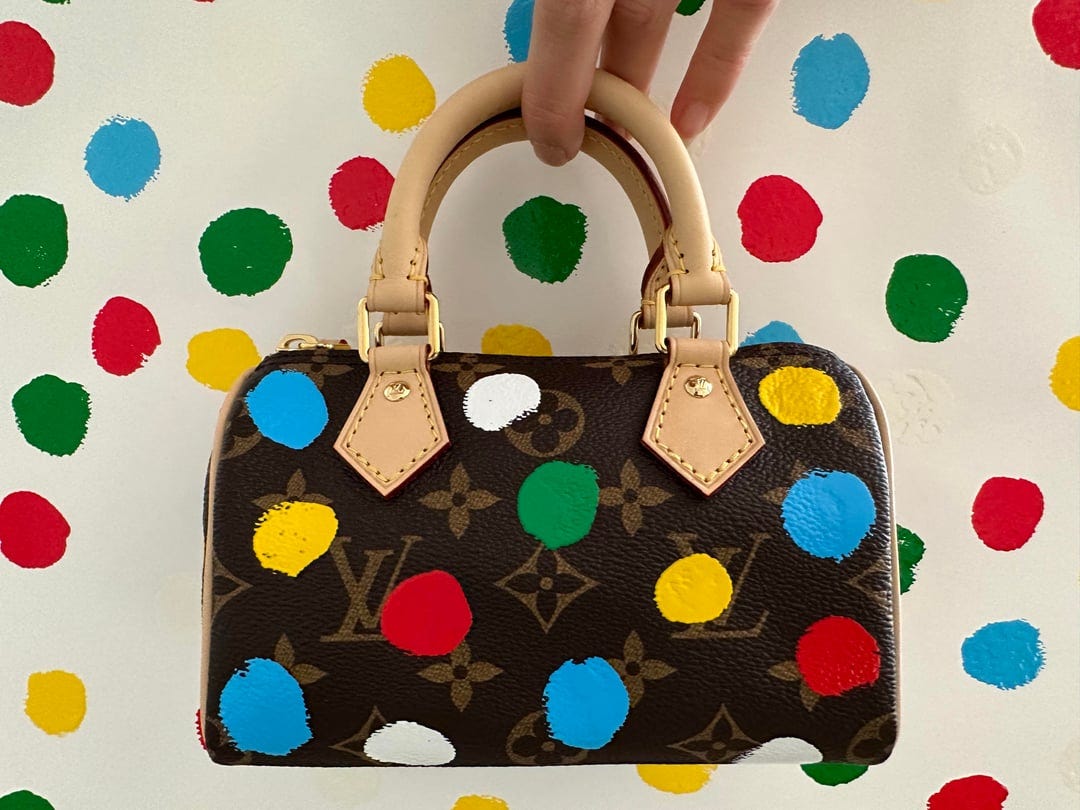
5. Luxury wants art’s credibility, and credibility cannot be rented
Luxury has become art’s most active suitor, and the courtship is now measurable.
Bernstein has published a quantified assessment ranking which luxury groups are winning the association with art, placing LVMH first, Kering second, Chanel third, scored across museum sponsorship, landmark restoration, and artist and architect collaborations. HSBC runs a parallel framework. The motive is rational: in a de-globalising world, brands need globally legible prestige, and art supplies it. The pricing power is real, too. HSBC noted that Louis Vuitton’s Nano Speedy carrying Yayoi Kusama artwork retailed at £1,740 against £1,260 for the plain monogram. The original Louis Vuitton and Murakami partnership is estimated to have generated more than $300 million.
But association is not commitment, and the difference is becoming visible. When LVMH revived the Murakami collaboration, much of the commentary read it as a brand monetising a famous name during a luxury slowdown rather than deepening any patronage. A serious partnership takes risk, time, and a willingness to let art stay difficult. A weak one turns art into atmosphere and an artist into set dressing.
Watch for: whether a brand funds the actual work, protects complexity, builds relationships across years rather than seasons, supports institutions, and accepts that art is not content. Duration tells you more than budget.
6. The market is localising, and almost no one is talking about it
This is the quietest structural shift in the data and possibly the most important.
Across every dealer segment, sales are moving toward domestic buyers. The smallest dealers now make 71% of their private sales locally, up nine points in a year. Even dealers above $10 million in turnover, where international collectors traditionally dominate, see local sales rising to 29%.
The cause is not mysterious. Tariffs, cross-border friction, shipping inflation, and administrative drag have made dealing across borders more expensive and less certain. Over 56% of dealers say US tariff policy has hurt their business. Among mid-tier auction houses the figure is 80%, and not one auction house surveyed reports a positive effect. You can see the same retreat in the regional splits: Hong Kong, the most international of the Chinese markets, fell 6% while the more domestic mainland rose 5%.
A market built on international circulation is quietly retreating into national rooms. That reshapes which fairs matter, which cities hold their artists, and where a gallery can actually sell.
Watch for: where collectors buy relative to where they live, which fairs still pull genuine cross-border money, and which “international” galleries are now running on local demand.
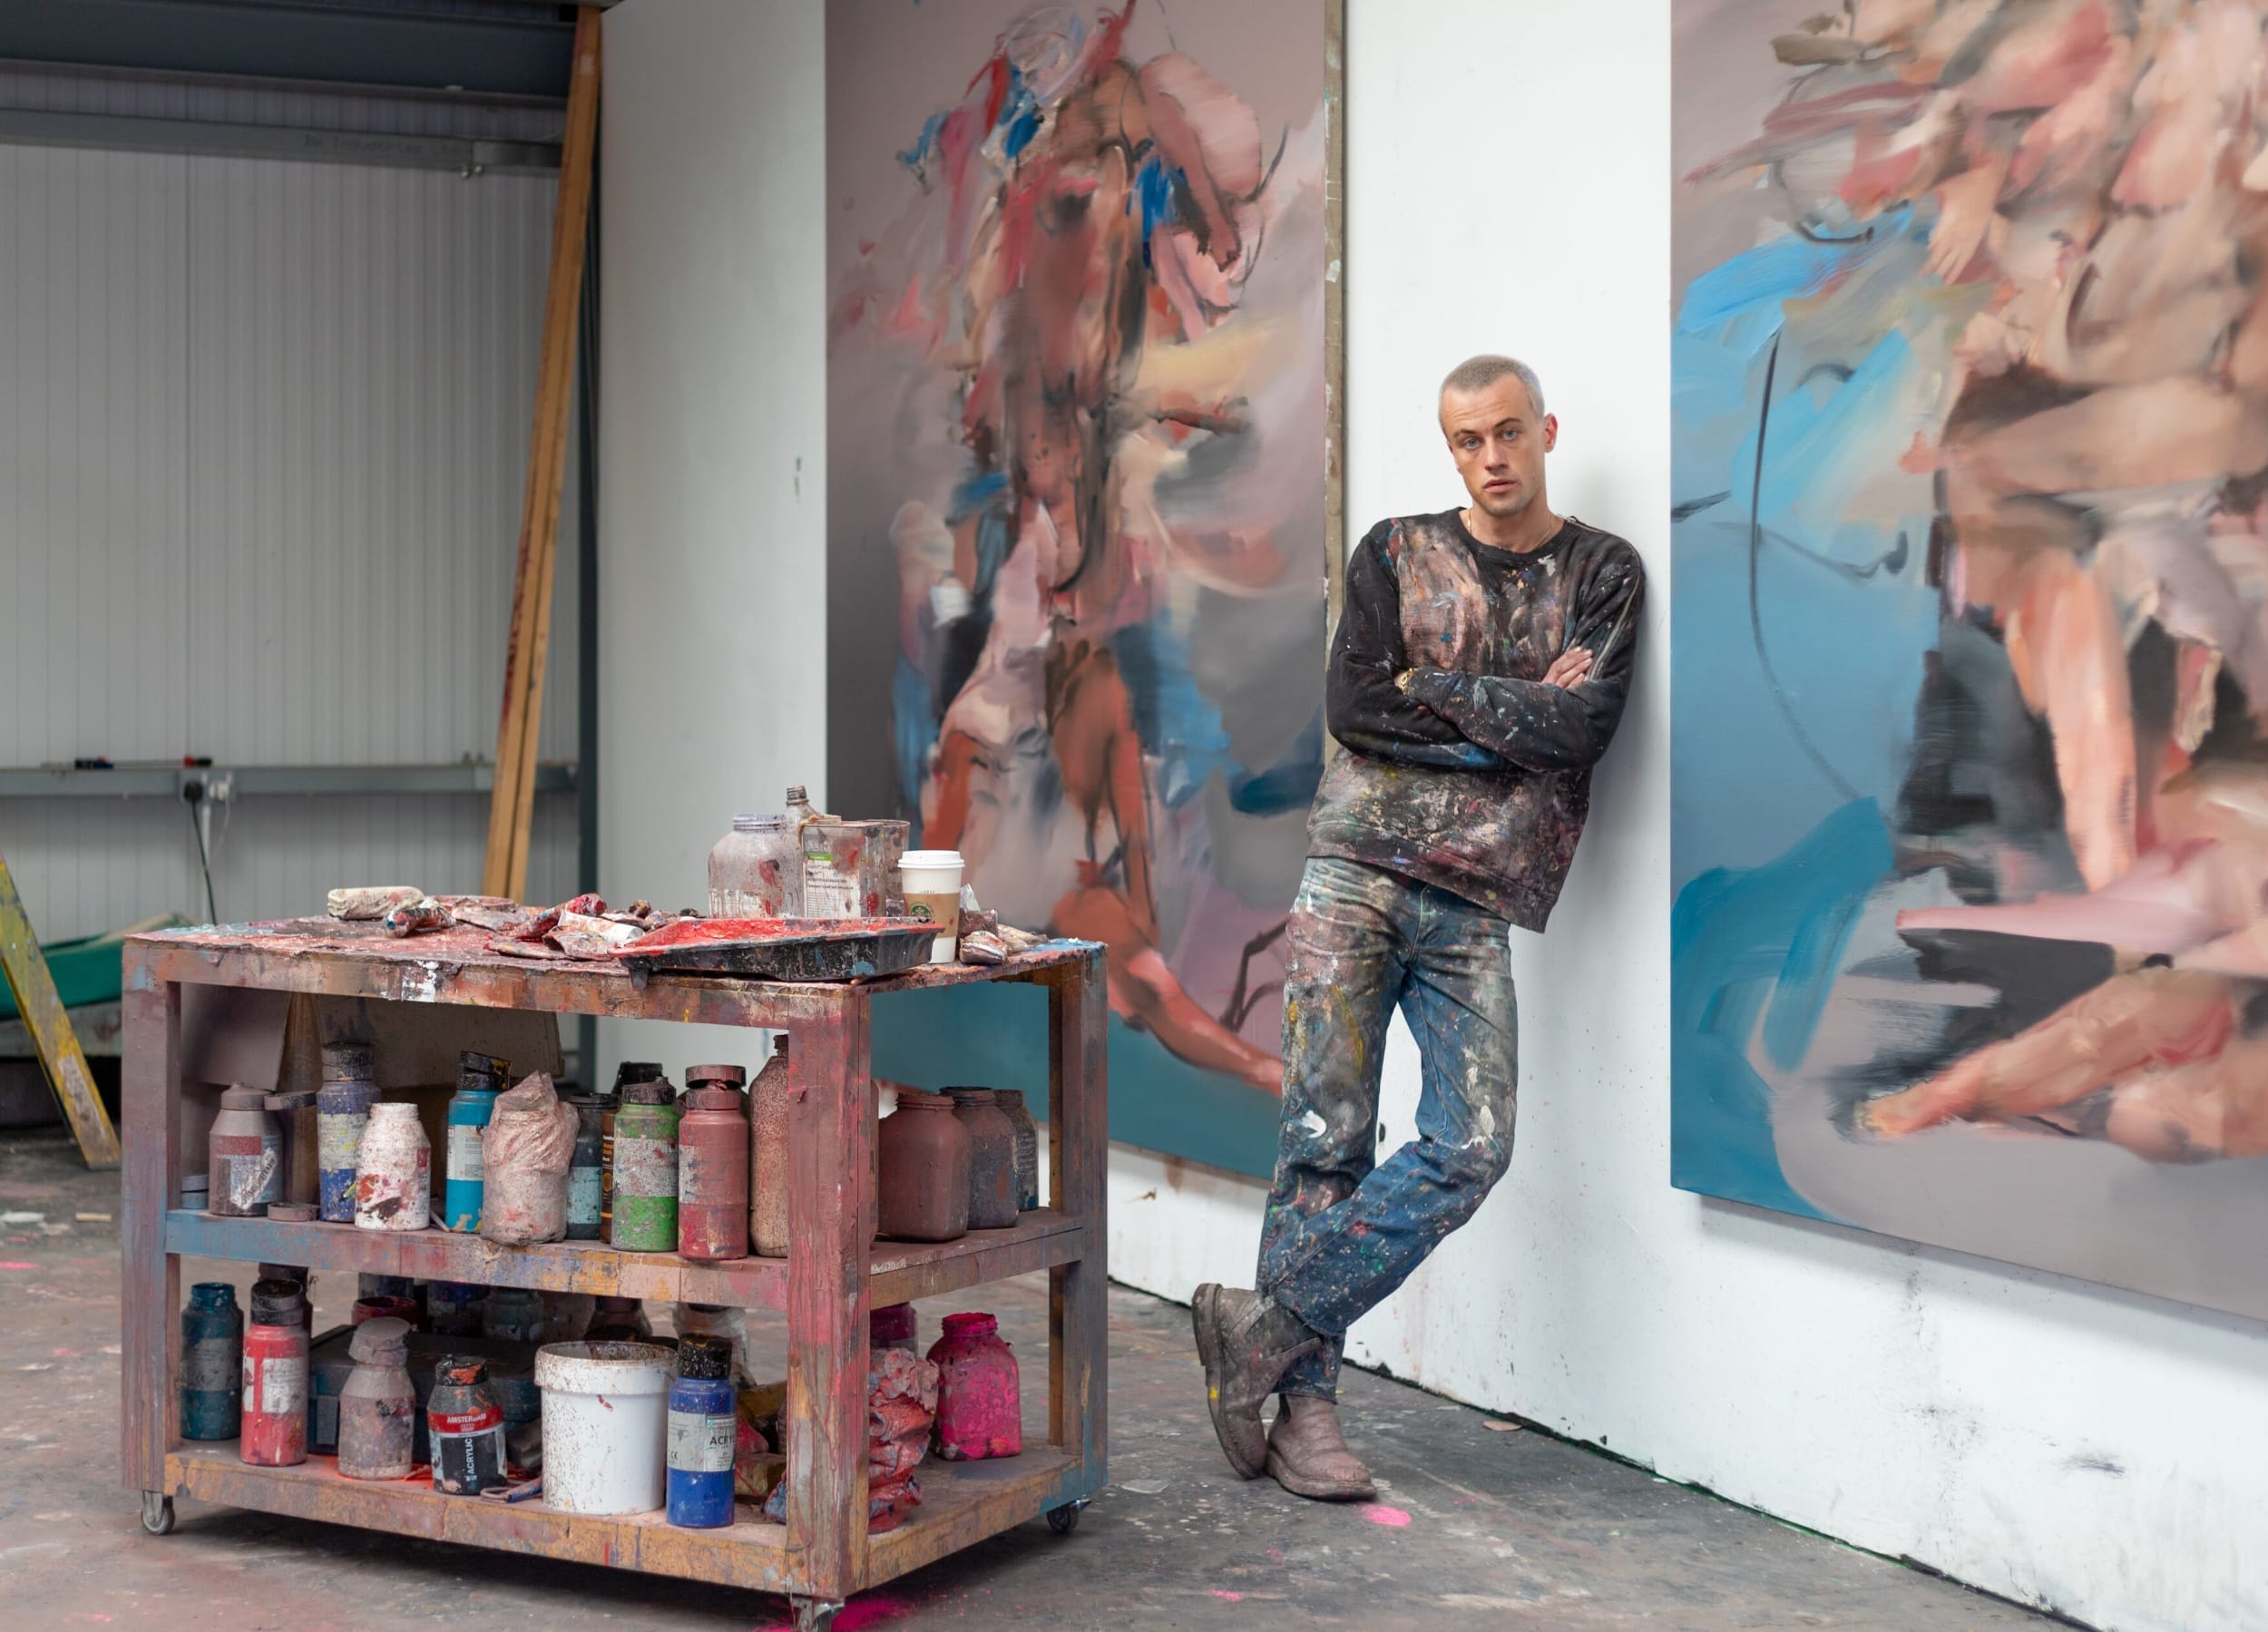
7. The strongest emerging artists are building systems, not moments
A single strong body of work creates attention. A career requires a system.
The data keeps rewarding the distinction. As ultra-contemporary speculation collapsed, demand moved toward established names and work with track record. Impressionist and Modern art has overtaken postwar and contemporary as the most lucrative auction category at $4.7 billion, up 29.5%, and Old Masters jumped 41.2% to $708.6 million. The spring 2026 records ran the same way, through Pollock, Rothko, Brâncuși, Miró, names with a century of validation behind them. Collectors are paying for durability and art-historical certainty, not novelty.
The artists worth watching are not only making compelling objects. They are building a language, a rhythm, a set of questions, and a relationship to context that survives the first wave of attention. A market can run on novelty. A career cannot.
Watch for: repetition with development rather than repetition as formula. The strongest artists know exactly what they keep returning to and why. The weakest are repeating a winning product.
8. Institutional pace beats social velocity
Social platforms reward speed. Institutions move slowly. That gap is where the most expensive misreadings happen.
An artist can look essential online months before the slow structures of validation respond, and another can look quiet while accumulating residencies, acquisitions, curatorial interest, and catalogue essays. The first looks like momentum. The second often is. Female representation shows how slow real structural change is and how durable it becomes once it lands: women have reached 50% of artists at primary-market galleries, up from 36% in 2018, yet still only 27% of sales at galleries above $10 million. Representation moved through the slow institutional layer first and is only now reaching the top of the market.
The real signal is not how fast attention arrives. It is whether attention is converting into structure. Museum acquisitions, curator commitment, serious group shows, institutional collections, grants, prizes. Those are slow, and slow is the point. They are harder to manufacture, which makes them worth more as signals.
Watch for: the movement from visibility into structure. The artist whose feed is loud but whose institutional record is empty is a different proposition from the one whose record is filling while the feed stays calm.
The other twelve signals are where the market gets read before the price moves.
You have just read the eight signals shaping the surface of the market. The twelve below move underneath it, where confidence is set, supply is metered, and value is decided before any of it reaches a headline. This is the half of the map that rewards reading.
Inside the full Signal Map, for members of the Intelligence Desk:
9. Scarcity is no longer about supply.
10. The four questions every serious collector now asks before buying.
11. Why the smartest galleries are showing you less.
12. What a fair booth is actually for now.
13. The market most people never see, and how to read its temperature anyway.
14. The $992 billion that is about to move.
15. The guarantee is quietly rewriting what an auction result means.
16. The signal-maker the market cannot manufacture.
17. The clearest way to destroy an artist’s market.
18. The map is being redrawn.
19. Why provenance became the most valuable story an object can carry.
20. The only signal that actually matters.
One read, and you see the market the way the people setting its prices see it.
